Why 1stHF LLC does not take money under management
People often ask: “Where should I invest?” Sometimes the next sentence is: “Can I just send it to you? You’re in the market.” That is a fair question. Our answer does not change with the amount, the country, or how well we know each other.
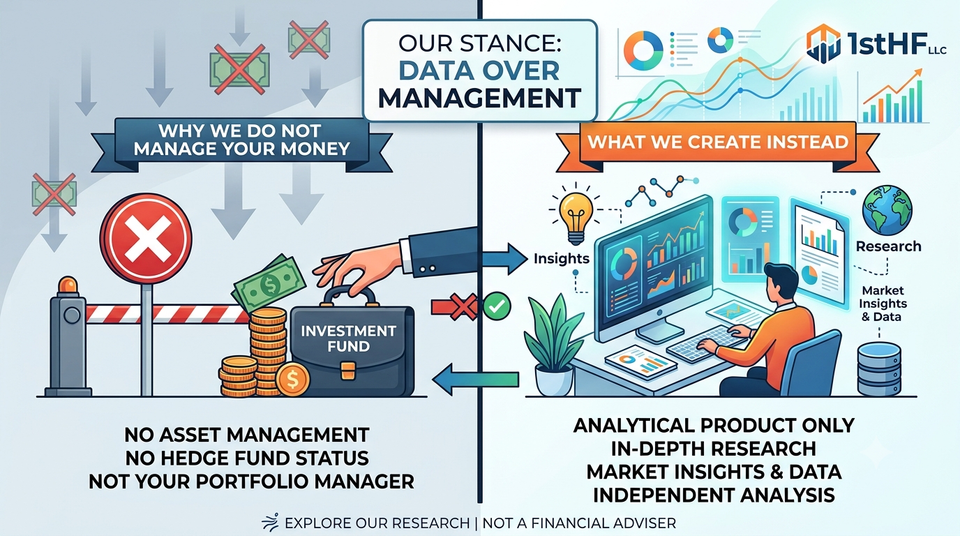
1stHF LLC does not accept funds under management. We are not a hedge fund, not a portfolio manager, and not a “dashboard you fund so we can buy stocks for you.” We build an analytics product.
This post explains that line in full: why we draw it so firmly, what we sell instead of management, and how a real fund differs from a polished client portal.
What we actually are
1stHF LLC is a U.S. company. We run 1sthf.com, the app at app.1sthf.com, and the tools around it: trend, screener, research, a trader workspace, a paper journal, digests.
That is market analytics and reference data for people who look at markets themselves. The point is to read the picture faster: price, filings, regime, ideas you can check on your own. It is not an order to “buy X with this much money.”
Inside the product you get a login, settings, symbol lists, charts. That is a software subscriber’s account, not an investor account in a fund. You may see a paper portfolio, an alert, a summary. You will not see “deposit a balance and we will allocate it for you.”
In short:
| We are | We are not |
|---|---|
| Software and analytics | A turnkey investment adviser |
| A subscription for access to a tool | Fees on assets under management |
| A subscriber workspace | A custody account |
| A research and education layer | A hedge fund |
If you mix those columns, you do not get a “natural product upgrade.” You get a different business — with different law, different liability, and different clients.
Two different jobs that sound like one question
“Where should I invest?” usually hides one of three jobs, not a single job.
1. Preserve. The person does not need to beat the S&P. They need not to lose purchasing power. They want dollars, a broad index, a clear horizon — or something that is not the market at all. That is a goal-and-risk problem, not a screener problem.
2. Get access. No usable brokerage account, no map of how U.S. markets work, fear of the wrong button. What helps is navigation: how an account works, what an order is, how a stock differs from a fund. The money still stays with that person, at their broker.
3. Hand off responsibility. “You do it. You know this.” That is a request for discretionary management: someone else’s capital, someone else’s stress, someone else’s drawdown at quarter-end.
We can help with the first two through the product and through explanations. We do not take the third. Not because we “don’t want to grow,” but because the third request is the profession of an asset manager, not an analytics vendor.
The confusion starts when a company has charts, a U.S. LLC, and a login. From the outside it looks like: if you already have a terminal, you might as well take the money. That is an illusion. Bloomberg does not run your account. A terminal and a fund are different markets.
Why “wire it to us, we’ll buy” is not a 1stHF service
Each of the following is enough to say no. Together they make “no” the only honest answer.
1. It is a different legal status
In the United States, selling access to a research interface and being paid to manage other people’s money or to give personalized investment recommendations sit in different regimes.
Managing capital and telling a specific person “buy this, in this size, for you” is investment-adviser territory. That means registration, conflict disclosure, custody rules, reporting, and a ban on mixing client money with the firm’s money. Exemptions exist. They are narrow. They are not “friends wired the LLC and we bought SPY.”
Pooling other people’s money in one company brokerage account is closer still to an unregistered fund. A logo in the site header does not change that.
We are not pretending that “because we are not a bank, it is fine.” The opposite: because we know what adult fund infrastructure looks like, we will not fake it with a screen.
This article is not legal advice. The point is simpler: we stay in the product lane on purpose. We do not promise a mandate 1stHF LLC does not have.
2. Client money must not live on our account
In a proper fund, securities sit with a custodian or prime broker. The manager makes decisions inside a mandate. The manager does not keep the wallet in a pocket. The investor reads a report; they do not rely on “the founder seems honest.”
If money lands on the founder’s account or on an operating company’s account, you no longer have investing. You have a mess:
- SaaS revenue and client capital become indistinguishable;
- a frozen bank account, a tax dispute, a corporate claim, a vendor lawsuit — and client money is in the same pile;
- a market loss gets a second question: “is the money even still there?”
So the 1stHF rule is simple: we do not take wires “for investing.” A subscription pays for product access. A brokerage account is yours, in your name, at a licensed broker.
A pretty balance in a dashboard with no independent custodian is not “fintech.” It is a promise nobody can audit.
3. “We trade for you” has a conflict built in
An analytics product earns money when people use it. The incentive is clear: data, speed, a readable interface.
A manager earns on assets or on performance — and the distortions show up immediately:
- it is easier to promise return than to explain a drawdown;
- it is easier to take one more client than to admit the strategy does not scale;
- it is easier to show winning trades and hide the method.
Even an honest person inside that model starts defending “but I took the money.” We do not need that. We want a user to be able to cancel a subscription and leave, with their capital never having been with us.
4. Being “in the market” is not a public track record
The market does not owe anyone confirmation. You can watch charts for years, write indicator code, keep a paper journal — and still have no right to call yourself a manager of other people’s money.
Someone who manages outside capital has to show rules in advance and results after costs and drawdown, not only a green year. Without that report, “I feel the tape” is not a product.
We do not sell the idea that trader tools in the app equal alpha on live client accounts. A tool helps you look. The decision and the risk sit with the person who hits buy on their own account.
If a separate, licensed story with an outside custodian and qualified investors ever exists, that will be another company and another contract, not “we shipped a module inside 1stHF.” It does not exist today. We will not tease a fund “soon, in the same dashboard.”
5. Borders, banks, and compliance
1stHF is a U.S. company. Users can be anywhere. That is normal for a software subscription: a card, access, an account.
Other people’s investments are not a subscription. Banks and brokers look at source of funds, citizenship, sanctions lists, origin of capital. Mixing LLC operating revenue, retail wires from several jurisdictions, and the phrase “we’ll put it to work” is a way to get an account closed faster than you get a working strategy.
We will not build a grey channel of “send it however you can, we’ll figure it out.” Cross-border money for management needs KYC, a custodian, and a real fund structure. That is slow and expensive. It is not a button in the app.
6. Trust is a fragile asset. Do not put it on a quote
This stays true even when everyone is “one of us” and everyone agrees. Markets draw down. A strategy that looks calm on paper feels different when it is someone else’s live money.
When you lose your own money, that is your lesson. When you lose money from someone who came because “you’re in this,” you do not owe “the market.” You owe them. In a small circle that lasts longer than any website disclaimer.
1stHF is meant to be a long product. We would rather remain a company that does not mix personal trust with running someone else’s account.
How a real hedge fund differs from a login on a website
In casual speech, “hedge fund” means “smart people turn the money.” In the industry it is a stack of roles. Layout cannot replace them.
A separate fund vehicle. Not the operating software company, and not “the same LLC, we’ll just add a sub-account.” Investors enter a fund through documents: a memorandum, a subscription, investor qualification.
An adviser. The party that makes investment decisions, discloses conflicts, and lives under the regulator in the place where it actually operates.
A custodian. An independent holder of the assets. The founder must not be able to “move it to a card.”
An administrator and an auditor. They compute NAV, send investor reports, and check that the number in the dashboard is not an HTML graphic.
Who is allowed in. Not anyone who asks “where should I invest.” Typically qualified or accredited investors, caps on the number of participants, and a ban on retail marketing that sounds like “a deposit, only higher yield.”
Time and cost to launch. Counsel, registration, a prime broker, compliance, reporting — years and a real budget, not a UI sprint.
Until that stack exists, the honest sentence is: we are not a fund. The 1stHF workspace shows data and your settings. It does not show a partnership interest in a fund, because we do not sell one.
Faking NAV, “assets under management,” and a live performance chart on other people’s money without that infrastructure is promising someone else’s business. We will not do that.
What “account” means here
At 1stHF an account is:
- a subscriber login;
- your lists, alerts, saved symbols;
- access to analytics sections;
- paper / practice workflows, if you use them;
- theme, digest, and session settings.
It is not:
- funding an “investment balance” to our bank details;
- a yield promise;
- a “delegate management” button;
- a mix of your money and company money.
If you see a similar interface somewhere else where you can “deposit funds, we’ll place them” — that is a different product type. Do not compare us to that storefront. We refuse to build it.
What we sell instead of management
Refusing client capital does not mean we offer nothing. It means: pay for the tool and for product work, not for the right to park risk with us.
A subscription. Access to the app and to site materials. 1stHF revenue is SaaS, not 2% of assets.
Reference analytics. Trend, screener, fundamentals, news, supporting metrics. That speeds up your own work. It is not a personal recommendation sized to your household.
An education layer. How a screen works, what a metric means, which steps people usually take before a trade: goal, horizon, position size, where the account sits. Verbs about the interface and the process. Not “buy this ticker tomorrow.”
An honest reply to “where should I invest,” in our frame, sounds like this:
- first the goal and the time (preserve / grow / speculate — different games);
- then your own account at a broker you choose;
- then a risk you are willing to see in a drawdown, not only in a gain;
- only then any tools, including 1stHF, as a map of the terrain.
We can help you read the map. We will not drive the car with your money.
What we will not promise — on purpose, as a list
So there is no ambiguity.
- We do not take funds “to put to work,” “into a pool,” “onto a shared account,” or “to hold for a while.”
- We do not promise return, “like a deposit,” or “we’ll give it back with interest.”
- We do not sell individual trade instructions sized to your capital as a management service.
- We do not assemble a hedge fund “on top of the app” without a separate licensed structure and an independent custodian.
- We do not use the operating company as a piggy bank for client investments.
- We do not treat paper results in the app as a guarantee for a live account.
If what you need is discretionary management, that is another market: a licensed adviser or fund, a contract, a custodian, investor qualification. We can still be your analytics vendor if you are already there. We will not impersonate that firm.
Why we published this
Silence reads as “we can work something out.” For 1stHF that is not true.
A product company in markets stands on a slippery line. One “okay, wire it, I’ll buy” and you are no longer in software. After that, compliance breaks, the meaning of the subscription breaks, and you lose the right to say, honestly: the data is for reference; this is not investment advice.
We choose the boring side. In finance, the boring side is usually the one companies survive on.
If you came for a terminal, a screener, trend, research — you are in the right place. If you came to hand over capital “turnkey” — you want a licensed manager, not us. We do not resent that request. We simply do not answer it with a service we do not offer.
In one paragraph
1stHF LLC does not take money under management because we are not a fund and we will not pretend to be one. We sell analytics and access to a tool. Your money stays in your account. Our workspace is for working with data, not for custody.
A real hedge fund is separate legal entities, a regulator, a custodian, an auditor, and a narrow investor set. It is not “add a balance to the dashboard.” Until we have built that, we will not costume it.
Thank you for reading us as a mapmaker, not as a holder of capital. That is the design.
Prepared by 1stHF LLC. This article explains what our product is. It is not personalized investment, tax, or legal advice. Market data in the app is for reference. Trading decisions and the choice of broker are yours alone. If you need asset management, contact a licensed intermediary in your jurisdiction.